
Car Hire Excess Insurance: Should You Buy It Separately?
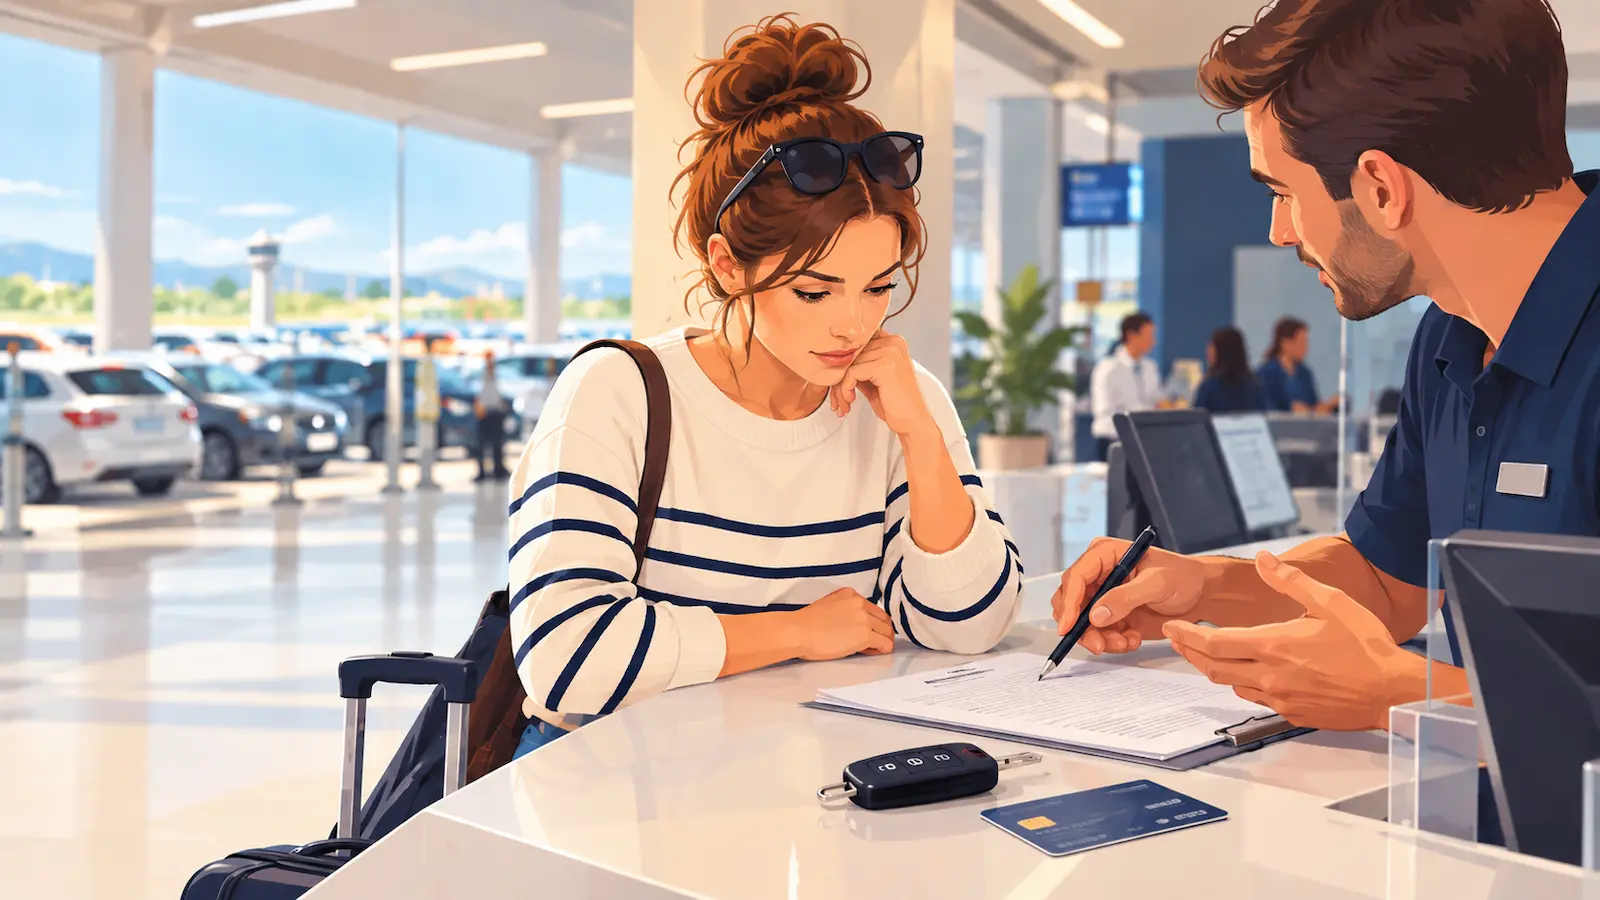
You’ve found a good deal on a hire car in Spain. The booking says insurance is included. Then, in the small print, you spot it: if the car is damaged, you could still be liable for an excess of £1,000 or more.
At the booking stage, or later at the desk, you’re offered a way to make that go away. It costs a lot more than you expected. Then you discover you can buy standalone car hire excess insurance online, for the whole trip, for less than the price of a round of drinks.
Which raises the obvious question:
If £15 of standalone insurance can cover a £1,000+ excess, why would anyone pay the hire company ten times that?
Because they aren’t buying the same thing.
This guide explains the difference by following the money after the car comes back damaged: who can charge you, who pays first, and what you have to do to get your money back.
This is general information, not insurance advice. What you’re covered for depends on your rental agreement and any policy you buy, so check them before relying on anything here.
The quick answer
You have three choices.
- Accept the standard excess. Pay nothing extra, and accept that if the car is damaged or stolen, you could pay up to the excess on your rental agreement.
- Buy standalone car hire excess insurance. The excess stays in your rental agreement. If the hire company makes an eligible charge, you normally pay it first and then claim it back from your insurer.
- Buy the hire company’s own extra protection. Pay considerably more, but reduce, or sometimes remove, the amount the hire company can charge you for covered damage.
The distinction that matters most:
Standalone insurance reimburses your loss. The hire company’s protection changes what the hire company can charge you in the first place.
Everything else in this guide follows from that.
And whichever you choose, none of them records what the car looked like when you collected it. That’s still your job. (More on that below.)
What insurance does your car hire already include?
For a UK resident hiring in the UK or Europe, the price you’re quoted usually includes three things:
- Third-party liability: cover for damage or injury you cause to other people and their property.
- Collision Damage Waiver (CDW) and theft protection: these limit how much you have to pay if the hire car itself is damaged or stolen.
- An excess: the amount you’re still responsible for, even with CDW.
That’s the usual structure, not a universal one. Always check your own booking.
The key word in CDW is waiver, not insurance. It doesn’t mean “I can’t be charged for damage.” It means the hire company has agreed to cap what it can charge you, at the excess.
And the excess is rarely small. MoneyHelper, the government-backed guidance service, says most car hire companies charge an excess of between £500 and £1,500 if the car is damaged or stolen. For a real example, Enterprise’s current fee schedule for Spain lists excesses from €1,250 to €2,500 depending on the vehicle, with a €1,400 excess for many smaller cars.
So “insurance included” usually means: for damage covered by the waiver, you’re paying up to the excess rather than the full cost of the car.
The car is damaged. What happens now?
Here’s a scenario. You’ve hired a small car in Spain. The booking includes CDW with a €1,500 excess. On the last day, you clip a kerb and scrape a wheel. At return, the hire company says the repair will cost €600.
What happens next depends on which choice you made.
| You chose… | What can the hire company do? | Do you pay first? | Separate claim needed? | Who you deal with |
|---|---|---|---|---|
| Standard cover (accept the excess) | Charge you for eligible damage, up to the excess | Yes | No | The hire company |
| Standalone excess insurance | Charge you under the rental agreement, exactly as above | Usually yes | Yes, with your excess insurer | Hire company + your insurer |
| Hire company’s excess reduction | Charge you only what’s left after the reduction, often nothing for covered damage | Reduced, or nothing | Usually no | The hire company |
A few things jump out.
With standalone insurance, the hire company’s side of the story doesn’t change. It can charge you under the rental agreement just as it could if you’d bought no extra protection. The difference comes later, when you claim the €600 back.
Only the hire company’s product changes what happens at the desk. It’s the one option where a covered €600 wheel may simply not become your problem.
“Covered” doesn’t mean “never out of pocket.” With standalone cover, you may be €600 down until your claim is paid.
That’s the cash flow. Keep it in mind for the rest of this guide.
What is standalone car hire excess insurance?
It’s a separate insurance policy, bought from a specialist insurer or broker rather than the hire company. It sits completely outside your rental agreement.
That’s the crucial point. It doesn’t persuade the hire company to waive its excess. The hire company isn’t a party to it, and generally doesn’t care that you have it.
Instead, if the hire company charges you for something your policy covers, you claim that amount back from your insurer. ReduceMyExcess, one UK provider, describes it plainly: the rental company “will normally claim the excess directly from your credit card,” and “it is this amount” its policy then reimburses, up to its £10,000 limit.
That’s also why it can be so much cheaper. It isn’t a worse version of the hire company’s product. It’s a different product:
- the hire company’s protection changes the contract;
- standalone insurance reimburses you after the contract has been enforced.
One takes the risk away at source. The other pays you back afterwards.
Standalone insurance doesn’t make your excess disappear at the desk
This is the misunderstanding that catches people out.
You’ve bought your standalone policy. You arrive at the desk, and you think:
“I’m insured, so they don’t need my credit card.”
They do.
As far as the hire company is concerned, you haven’t bought any extra protection from it. Your excess is exactly what it was, and it can apply its normal deposit or pre-authorisation rules. Your insurer’s promise to reimburse you later doesn’t change any of that.
Deposit and excess are not the same thing.
The excess is the most you can normally be charged for damage covered by the waiver. The deposit (or “security deposit”, or “pre-authorisation”) is money the hire company blocks on your card while you have the car. The two are often related, and the deposit may be set with the excess in mind, but they aren’t automatically the same amount.
This is one of the most legitimate reasons to buy the hire company’s product despite the price. Which?’s car hire research highlights one important advantage of buying at the desk: you may avoid having to leave a large deposit or pre-authorisation on your card. Goldcar, for example, says its own Super Relax cover lets you hire “without excess” and reduces the security deposit on your card.
If you’re relying on standalone insurance, the practical question is simple: can your credit card comfortably take the deposit, and could you cover a damage charge temporarily if you had to?
Your three choices, side by side
Keep the risk: accept the standard excess
What you pay: nothing extra.
What stays with you: everything up to the excess, plus anything the CDW doesn’t cover (check the exclusions).
The trade: This is a legitimate choice, not a reckless one. If you can comfortably absorb £1,000 or £1,500 and you understand what’s excluded, you may decide not to insure it. Just make that decision knowingly, rather than by default.
Insure it elsewhere: buy standalone excess insurance
The case for it:
- often dramatically cheaper;
- policies can cover areas the hire company’s basic waiver often excludes, such as tyres, glass and the underside of the car;
- single-trip and annual policies are available;
- reimbursement limits can be high.
The case against it:
- your rental agreement doesn’t change;
- the hire company can still take a large deposit;
- you may have to pay a damage charge first;
- you have to make a separate claim;
- exclusions and paperwork matter.
Pay the hire company to reduce it: buy its extra protection
It goes by many names: Super CDW, excess reduction, zero excess, premium protection, Super Relax. Whatever it’s called, it’s the hire company agreeing to lower what it can charge you.
The case for it:
- it changes your liability under the rental agreement itself;
- it’s simpler if something goes wrong;
- it may reduce the deposit on your card;
- you avoid paying a big charge and reclaiming it;
- you deal with one company, not two.
The case against it:
- it’s often dramatically more expensive;
- it still has exclusions;
- “zero excess” or “full protection” doesn’t automatically mean every type of damage or charge is covered.
MoneyHelper warns that hire company top-up products “tend to exclude theft, vandalism, damaged tyres, lost keys and use of wrong fuels”. Not all do, but read what yours includes before assuming the word “full” means full.
None of these choices is always right. They’re different trade-offs between price, cash flow and hassle.
What does standalone excess insurance actually cover?
Don’t judge a policy only by the headline excess it will reimburse. The detail is where policies differ. Check:
- bodywork;
- wheels and tyres;
- windscreen and glass;
- roof;
- underbody;
- keys;
- towing;
- misfuelling;
- administration charges;
- loss of use (what the hire company charges for the time the car is off the road);
- theft;
- the maximum reimbursement;
- the maximum hire length;
- vehicle value and type restrictions;
- where you’re covered.
Current policies show why. Questor lists £10,000 for excess reimbursement and for tyres, windscreen, roof and underbody, but separate, lower limits for other things: £500 for administration charges, £1,000 for towing, £1,000 for misfuelling and £750 for keys. ReduceMyExcess lists tyres, windscreen, undercarriage, misfuelling, towing, keys and loss of use among its standard benefits, again with a £10,000 excess-reimbursement limit.
Those are examples, not recommendations. The point is simpler:
Don’t compare policies only by the maximum excess they’ll reimburse.
A £10,000 headline limit is no help if the thing you actually damage sits under a £500 sub-limit, or isn’t covered at all.
How much does car hire excess insurance cost — and what are you paying for?
Standalone excess insurance can cost less for an entire trip than the hire company’s excess reduction costs for a single day.
That isn’t an exaggeration. When Which? priced a week’s hire of the smallest available car from Malaga Airport in July 2026, Cover4Rentals’ standalone policy cost £12.24 for the whole week. Europcar’s Premium Protection for the same hire cost £287 — about £41 a day.
More generally, ReduceMyExcess advertises single-trip UK and Europe cover from £2.15 a day, and MoneyHelper says daily standalone policies start at around £3.
So why would anyone pay more?
Because, as the table above shows, they’re paying for different things. The hire company is charging to change what it can charge you. The standalone insurer is agreeing to pay you back afterwards, if your claim is valid. That difference has real value:
- no damage charge to fund and reclaim;
- potentially a smaller deposit on your card;
- one company to deal with;
- no claim form, no waiting for reimbursement.
Part of the price difference is the price of convenience.
The mistake isn’t choosing one or the other. It’s comparing only the daily price and not what you’re actually buying.
Single-trip or annual?
Single-trip cover makes sense if you expect to hire a car once in the next year.
Annual cover becomes worth checking surprisingly quickly. ReduceMyExcess, for example, currently advertises single-trip UK and Europe cover from £2.15 a day and annual cover from £47.30, and suggests annual cover if you’re hiring on two or more separate occasions within 12 months. MoneyHelper puts annual policies at from around £39.
There’s no magic number of days at which annual always wins; it depends on the prices you’re quoted and how you travel. But the practical rule is simple:
If you expect to hire a car more than once in the next 12 months, check the annual price before buying single-trip cover.
Before you buy excess insurance, make sure you actually have an excess
This sounds obvious. It isn’t always.
Standalone excess insurance is designed to reimburse the excess left by the hire company’s CDW (or equivalent). It assumes that basic damage protection is already in place, and that your liability is capped at the excess.
If your booking doesn’t include CDW, you may not have an excess at all. You could be liable for the full cost of repairing, or replacing, the car. An ordinary excess policy wasn’t built for that gap.
Most UK and European hires do include CDW. But not all of them: Which? has reported at least one major hire company offering rentals in the UK and Europe without basic CDW included.
Read the booking. Confirm that CDW, or equivalent damage protection, is actually included before assuming an excess policy fills the gap.
British doesn’t necessarily mean UK resident
Here’s a trap that most “best excess insurance” lists ignore.
Insurance eligibility often depends on where you live, not your passport.
You’re British, but you moved to Spain two years ago. A policy sold only to UK residents may no longer be available to you.
Current UK policies make this explicit. ReduceMyExcess says it is “not authorised to sell insurance to non-UK residents” and points EU residents to a sister brand. Questor requires customers to be permanently resident in the UK, the Isle of Man, the Channel Islands or Gibraltar.
Insurers don’t all define residence in the same way. But the lesson holds for any policy: check the residency rules before you buy. Buying a policy you weren’t eligible for isn’t a saving; it’s a claim waiting to be refused.
The insurance irony: buying cover can make your evidence more important, not less
Here’s the part that surprises people.
It’s tempting to think: “I’ve got cover, so I don’t need to worry about checking the car.” But look back at the table.
With the hire company’s own protection, a covered incident is often settled between you and the hire company.
With standalone insurance, a damage charge can raise two separate questions:
- Was the hire company entitled to charge you at all? Was the damage already there when you collected the car?
- Will your standalone policy reimburse the charge?
Your evidence matters for both. You don’t want to pay (or claim) for a scratch you didn’t cause, and your insurer will want to see the paperwork before it pays you. ReduceMyExcess, for example, lists the rental agreement, the damage report and invoices, repair receipts and photographs among the documents a claim may need.
Keep these, whatever cover you have:
- your rental agreement;
- the collection and return condition reports;
- any damage report from the hire company;
- the itemised repair or damage invoice;
- proof of what you paid;
- all correspondence with the hire company;
- a police report, where one was required;
- timestamped photos of the car at collection and at return.
Insurance protects your money. It doesn’t prove when a scratch appeared.
Before you drive away, document the car as though you might have to prove its condition later. Walk around it and photograph each side, the corners, the wheels, the glass and the interior, and photograph the dashboard showing mileage and fuel. Do the same when you return it. Those photos show the car’s condition whichever insurance route you chose.
Our Rental Car Inspection Checklist covers what to photograph.
Rental Car Proof walks you through the photos at collection and return, and records when and where you took them. It won’t guarantee a dispute or claim succeeds, but it gives you a clear, organised record if you ever need one. Get Rental Car Proof →
Hiring in the USA or Canada? Don’t assume the European model applies
Everything above assumes the usual European set-up: CDW included, with an excess on top. North America can work differently.
In the USA and Canada, the price you’re quoted may not include damage cover for the car at all. The equivalent of CDW (often called a Loss Damage Waiver, or LDW) can be an optional extra, and liability cover can vary by location.
Before you buy anything, establish whether your booking includes:
- CDW or LDW;
- theft protection;
- third-party liability;
- any excess (Americans call it a deductible).
Then check whether the policy you’re considering provides the missing protection, or merely reimburses an excess. They aren’t the same.
UK excess providers recognise the difference themselves. ReduceMyExcess, for example, offers optional CDW cover of up to US$50,000 on some worldwide policies, because US and Canadian rentals may not include it.
This deserves a guide of its own; for now, the key point is: don’t buy a European-style excess policy for a North American hire until you know what the hire actually includes.
Before you book: a quick checklist
- Is CDW (or LDW) included, and what’s my excess?
- What does the basic waiver exclude?
- What deposit or pre-authorisation will the hire company take?
- If I buy standalone insurance, do I have enough available credit for the deposit, and could I cover a damage charge temporarily?
- Does the standalone policy cover where I live, and where I’m hiring?
- Does it cover this vehicle and this hire length?
- Are wheels, tyres, glass, roof and underbody covered, and at what limits?
- Would annual cover be better value if I’m hiring again this year?
- What documents would I need to make a claim?
FAQ
What’s the difference between car hire insurance and car hire excess insurance?
Your hire normally includes basic protection such as third-party liability and, in many UK and European rentals, Collision Damage Waiver (CDW) and theft protection. Car hire excess insurance is separate cover for the amount you’re still responsible for under that protection. It usually reimburses an eligible excess after the hire company has charged you.
Is car hire excess insurance worth it?
It can transfer a potential four-figure excess to an insurer for a relatively small premium, which is why many people buy it. But if you’re comfortable absorbing the excess yourself, and you understand what’s excluded, choosing not to buy it is a legitimate decision.
Is standalone car hire excess insurance accepted by hire companies?
“Accepted” is the wrong way to think about it. Standalone insurance generally doesn’t replace the hire company’s excess or change your rental agreement. The hire company deals with you as normal; your insurer reimburses you separately. If you’re told at the desk that your policy “isn’t accepted”, or pressed hard to buy the desk’s cover, our guide to car hire scams and tricks covers what’s going on.
Do I still need a credit card if I have excess insurance?
Usually, yes. Standalone insurance doesn’t normally change the hire company’s payment and deposit rules, so expect it to take a deposit or pre-authorisation as it would for any customer without its own extra protection. Check your hire company’s terms.
Does car hire excess insurance cover tyres and windscreens?
Many standalone policies do, but never assume. Check the policy wording, including any separate limits for tyres, glass, roof and underbody.
Should I buy annual car hire excess insurance?
If you expect to hire more than once in the next 12 months, compare the annual price with single-trip pricing before you buy. Annual cover can work out cheaper surprisingly quickly.
Can I buy car hire excess insurance after collecting the car?
Generally, no. Buy it before you collect the car. ReduceMyExcess says it’s important to have your policy “before you collect your hire car”, and Questor’s policy doesn’t cover a hire agreement that started before the policy.
Does travel insurance include car hire excess?
Some travel insurance policies include car hire excess cover or offer it as an add-on, but many don’t, and cover varies a lot. Check your actual policy wording rather than assuming.
Do I need car hire excess insurance in Spain?
It depends less on Spain and more on your booking: what protection it includes, how big the excess is, what deposit you’ll need, and whether you’re comfortable carrying that risk yourself.
Whatever you choose, document the car before you drive away
Standalone excess insurance, the hire company’s extra protection or neither: none of them shows the car’s condition when you collected it. Your photos do.
Haven’t used it yet? Download the free Rental Car Inspection Checklist.
Sources
- MoneyHelper — Car insurance when driving abroad
- Which? — Car hire insurance
- ReduceMyExcess — homepage
- ReduceMyExcess — FAQs
- ReduceMyExcess — Single Trip vs Annual
- ReduceMyExcess — What is car hire excess insurance?
- Questor — Car Hire Excess Insurance
- Questor — Annual Car Hire Excess Insurance
- Enterprise — Rental Agreement Fee Schedule (UK, IE, FR, ES, DE)
- Enterprise — Spain fee schedule
- Goldcar Help — What is the Super Relax cover?
- Goldcar Help — What is the cost of additional cover?
- Goldcar Help — What is an excess and how does it work?
- GOV.UK — Hiring a car: what to watch out for
- Cover4Rentals — UK site
- Ageas — Car Hire Excess Waiver
- Insure&Escape — Can I add car hire excess insurance to my travel insurance policy?
- RAC — Car hire excess insurance